Quick answer
Startup business loans are harder to get than loans for established businesses, because there's little trading history to assess. Without property, most unsecured lenders want at least six months of trading. With residential or commercial property as security, a new business can often borrow from day one, from $20,000. Equipment finance and supplier terms can also help a startup get moving.
Key points
- Little trading history makes unsecured lending harder.
- Property security can fund a business from day one.
- Equipment finance helps with specific assets.
- Industry experience and a clear plan both help.
- Unsecured
- Usually needs around six months of trading
- Property-backed
- Possible from day one, from $20,000
- Helps
- Industry experience, deposit, clear plan
- Purpose
- Business purposes only
Starting a business usually costs money before it makes any. A café needs a fit-out before its first coffee, a tradie needs a ute and tools before the first job, and a franchise needs its fee paid before the doors open. The difficulty is that most lenders judge a business by its history, and a startup doesn’t have one yet.
That doesn’t mean startups can’t get funded. It means the route is different, and the fastest route usually involves property or the asset itself.
Your options as a new business
| Option | What it relies on | Available from | Speed |
|---|---|---|---|
| Property-backed loan | Equity in property | Day one | $20k to $250k possible same day (property-secured) |
| Equipment finance | The asset being bought | Often early, with experience | Quick for dealer purchases |
| Unsecured loan | Trading history | Usually after about six months | Fast once eligible |
| Supplier or franchisor terms | The relationship | Day one | Varies |
| Grants | Program criteria | Depends on program | Weeks to months |
Why property makes the difference
A property-backed lender has a second way to be repaid if the business struggles, so they can look past the lack of history. That’s why owners with equity in their home or an investment property often fund their startup this way, then refinance onto a business loan once the business has a track record.
It’s a real commitment, though. If the business doesn’t work, the property is at risk. Talk it through with everyone on the title before deciding.
What lenders look at for a startup
- Your experience in the industry.
- Your personal credit history.
- A clear plan, with realistic costs and income.
- Your own contribution, whether savings, a deposit or a trade-in.
- Security, if any.
Building up to unsecured lending
From the first day, run all income and spending through one business account, avoid dishonours and keep BAS lodged on time. After six months or so, that record is what unsecured lenders will look at. A clean first six months often opens the door to unsecured loans and lines of credit.
An illustrative example
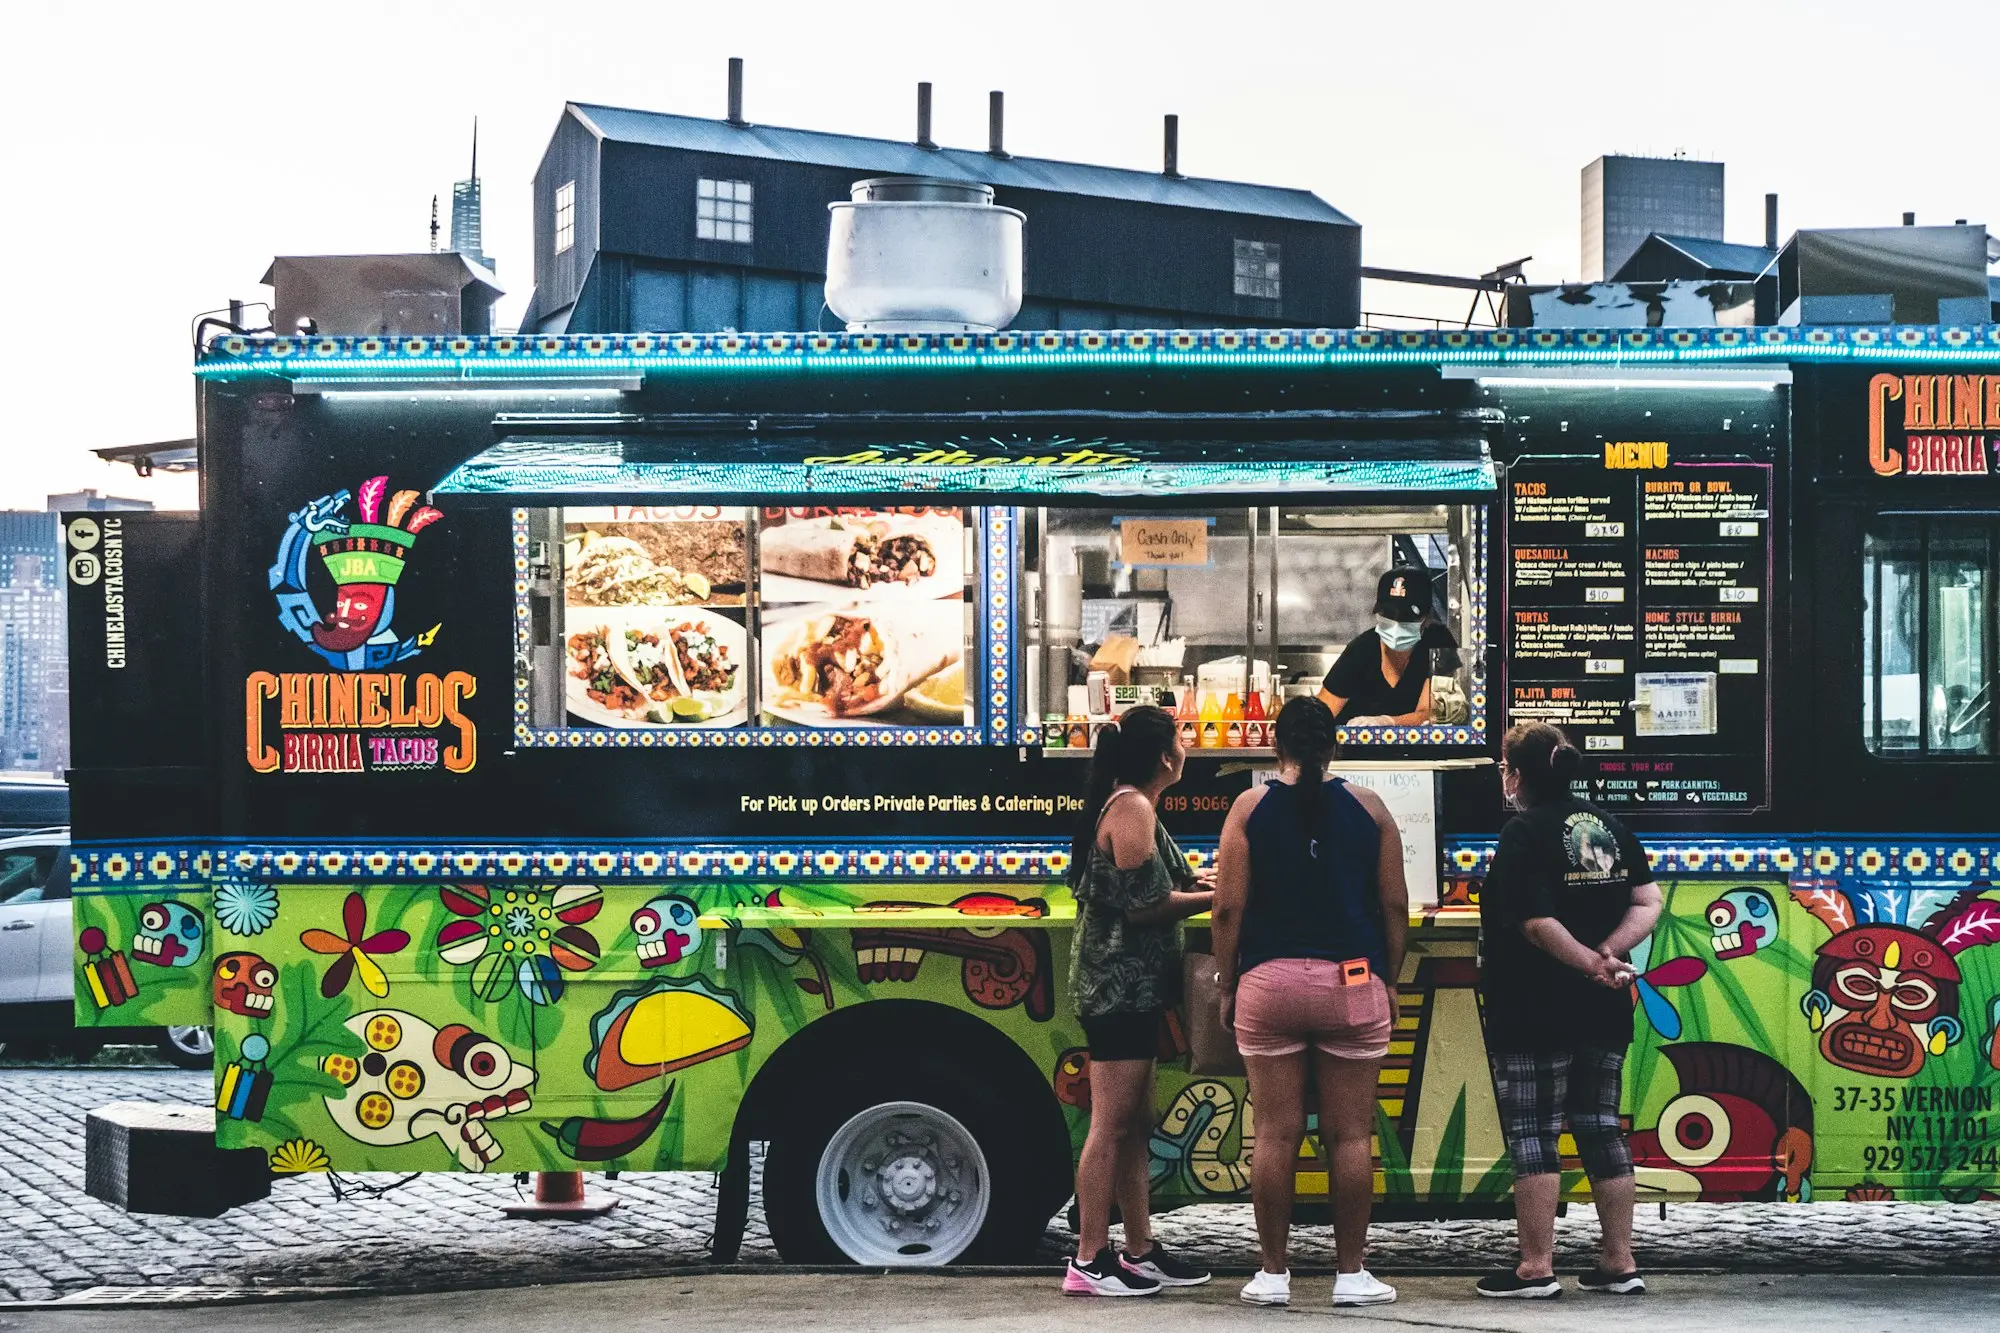
After twelve years as a chef, a Wollongong cook opens a food truck. The truck, fit-out and first month’s stock come to about $95,000. With no trading history, unsecured lenders aren’t an option. She and her partner have equity in their home, and a second mortgage over it funds the startup costs. Eighteen months later, with a solid trading record, the business refinances onto an unsecured loan and the second mortgage is repaid.
Startup traps to avoid
- Borrowing more than the plan needs.
- Using a personal credit card for business startup costs.
- Repayments that start before the business has income.
- Not budgeting for the first few slow months.
What to prepare before you ask
A startup enquiry moves faster when the basics are already written down. Have a one-page summary of the business: what it sells, who to, where, and why you’re the right person to run it. List the startup costs item by item with quotes where you have them, and show what you’re putting in yourself. Add a simple twelve-month cash flow estimate that includes the slow first months, not just the busy ones. If property is part of the plan, note the address, its rough value, what’s owing and who’s on the title.
None of this needs to be polished. A lender mainly wants to see that you’ve thought it through and that the numbers hang together. A clear, honest summary often does more for a new business than a long business plan, because it lets a real person understand the opportunity quickly and match it to the right type of funding on the first call.
If you’ve already signed a lease or a franchise agreement, include the key dates, because they often set the funding deadline.
Keep personal and business separate
Open a business bank account before you spend anything. Running every startup cost through it builds the record that unsecured lenders will look at later, and makes tax time much easier.
Starting up and need funding?
Tell us what you’re starting, what it costs and what you can offer as security. There’s no credit check to enquire, and we don’t send your details to a pile of lenders. A real person reads it and calls you with a realistic plan.
Please be accurate on the form, including your experience and any property, so the first option we bring you is one that can happen. Start your enquiry.
Frequently asked questions
Can I get a business loan with a brand new ABN?
Unsecured lenders usually want some trading history first. With property security, a new business can often borrow straight away because the lender relies on the property.
What can a startup loan be used for?
Fit-outs, equipment, vehicles, initial stock, a franchise fee or buying an existing business, as long as it's for business purposes.
Does experience in my industry help?
Yes. Years working in the same trade or industry, even as an employee, gives lenders confidence that the business can succeed.
Are there government grants instead?
Some grants and programs exist for specific industries and regions. business.gov.au lists current grants and is worth checking before borrowing.
How fast can a startup be funded with property?
Property-secured amounts from $20k to $250k are possible same day once the valuation, title and signing steps are complete.